0 Roof Financing: Smart 2025 Guide
Understanding the Real Deal Behind 0% Roof Financing
0 roof financing is a promotional loan option that lets homeowners pay for a new roof with zero interest charges—but only if you pay off the full balance within a specific timeframe, typically 6 to 24 months. Miss that deadline by even a day, and all the interest that was building up behind the scenes gets added to your bill, often at rates of 20% or higher.
Here’s what you need to know about 0 roof financing:
- Not truly “free money” – It’s deferred interest, not forgiven interest
- Strict payment deadlines – Pay off the full balance before the promo period ends
- High credit requirements – Usually need a score of 700+
- Retroactive interest risk – All accrued interest hits if you’re late or short
- Works best for disciplined budgets – Only choose this if you can pay it off on time
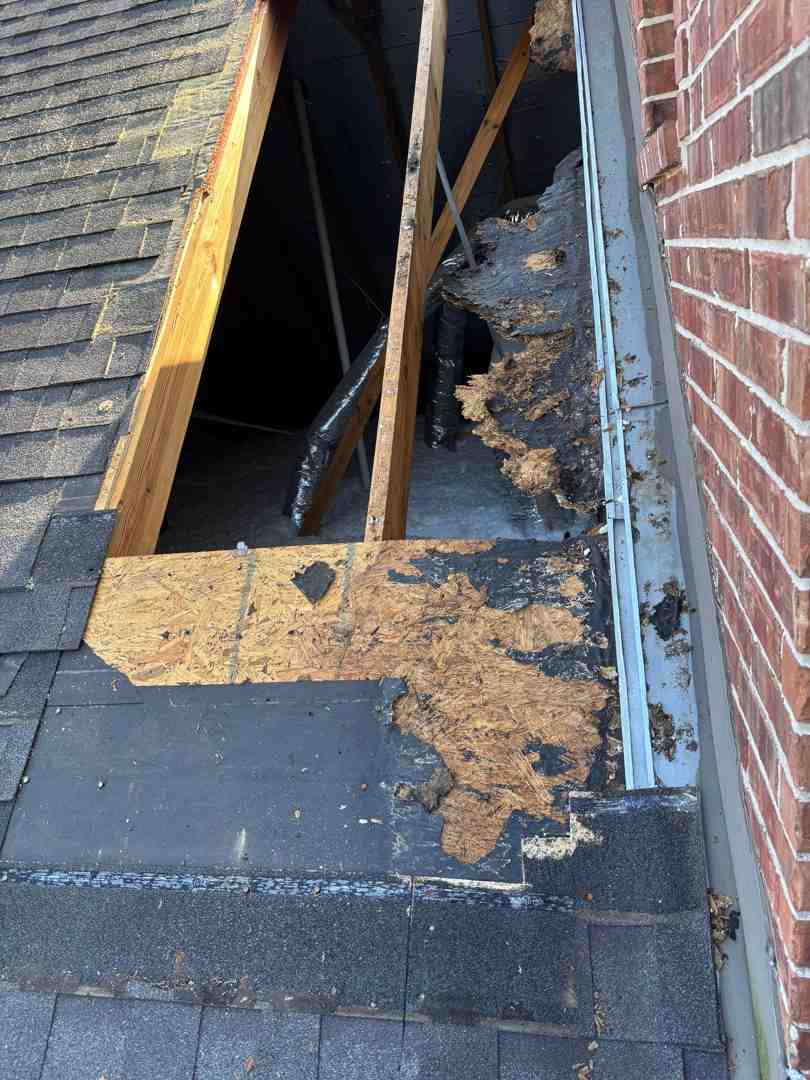
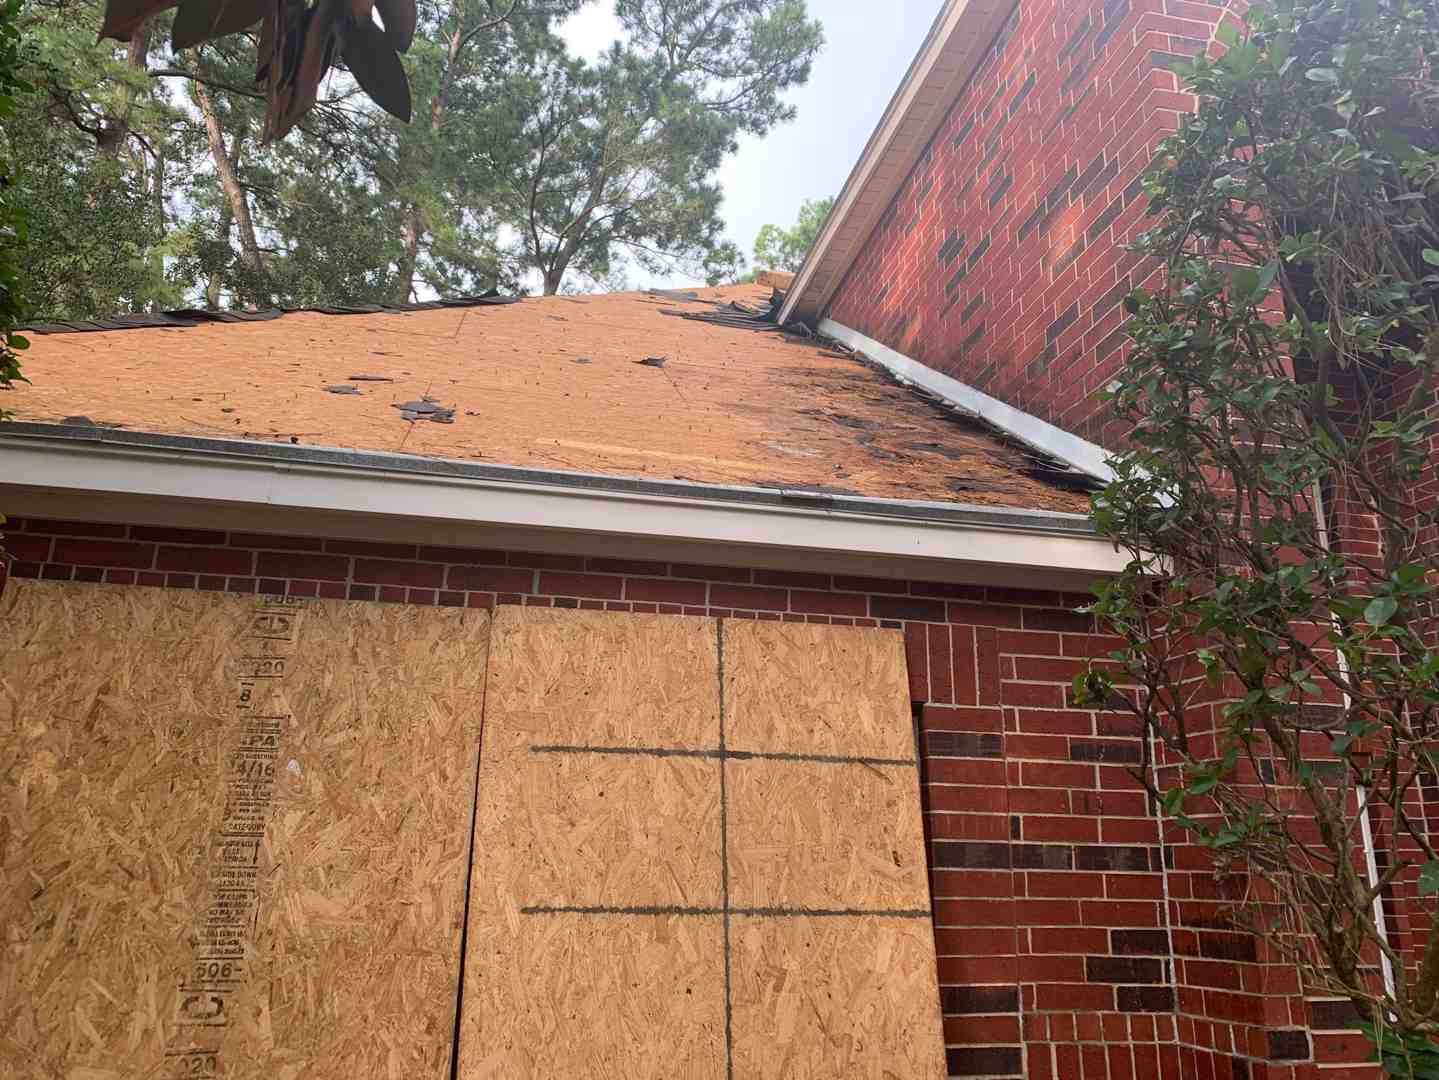
When your roof starts leaking or shows serious wear, the cost of replacement can feel overwhelming. In Texas, a typical 2,000 square foot home might need $10,000 to $15,000 for a complete asphalt shingle roof replacement. That’s a big number to come up with all at once, especially when storms, hail, or aging materials force your hand before you’ve saved enough.
Many homeowners in Katy, Texas, and surrounding areas like Richmond and Spring face this exact situation. Your roof protects everything—your family, your belongings, your entire investment. Delaying replacement because of cost can lead to water damage, mold issues, and even structural problems that cost far more to fix later.
That’s where financing comes in. Instead of draining your savings or putting off a critical repair, you can spread the cost across manageable monthly payments. But not all financing is created equal, and 0% interest offers deserve a closer look before you sign anything.
I’m David Shepherd, and through my work with Reliable Roofing & Restoration, I’ve helped hundreds of homeowners in the Katy area steer 0 roof financing and other payment options to protect their homes without breaking their budgets. Let me walk you through exactly what these deals really mean and whether they’re the right fit for your situation.
0 roof financing terms to learn:
The Truth About 0% Roof Financing Deals
We understand that when you’re facing an unexpected roof repair or replacement in places like Cypress, Katy, or Sugar Land, the idea of 0 roof financing can sound like a lifesaver. These are often presented as “same as cash” deals or promotional offers. Many reputable roofing companies, including us at Reliable Roofing & Restoration, partner with third-party lenders to make these options available. The goal is to help homeowners get the quality roofing services they need without the immediate financial strain. However, it’s crucial to understand the fine print before you jump in. These aren’t always as simple as they sound, and knowing how they work can save you a lot of headaches (and money) down the line.
How Does 0% Interest Roof Financing Actually Work?
When we talk about 0 roof financing, we’re usually referring to a deferred interest plan. This means you get an introductory period—often between 6 to 24 months, though sometimes longer, as some statistics show up to 60 months are offered in certain areas—during which no interest is charged on your purchase. Sounds great, right? The catch is usually in the “no interest if paid in full” clause.
During this promotional term, you might not have any payments due at all, or you might have small minimum payments that don’t cover the principal. The crucial part is that if you don’t pay off the entire principal balance before the promotional period ends, all the interest that would have accrued from day one is retroactively added to your loan. This can turn a seemingly interest-free deal into a very expensive one overnight. For example, a $10,000 roof replacement loan might accrue interest at 20-30% during that “0%” period. If you pay it off completely within the timeframe, you pay $0 in interest. If you’re even a dollar short or a day late, you could suddenly owe an additional $2,000-$3,000 (or more) in accumulated interest.
To avoid this retroactive interest, you essentially need to calculate your monthly payments so that the entire principal is paid off by the end of the promotional period. This often means making much higher payments than the minimums suggested by the lender. It’s a fantastic option if you have a lump sum coming (like a tax refund or insurance settlement for something other than your roof) or can budget aggressively to pay it down.
The Pros and Cons of 0% Financing
Like any financial tool, 0 roof financing has its advantages and disadvantages. We always encourage our clients in areas like Fulshear, Mission Bend, and Rosenberg to weigh these carefully.
Advantages:
- No Interest Paid (If Managed Correctly): This is the biggest draw. If you pay off the full balance within the promotional period, you essentially get an interest-free loan. This means every dollar you pay goes directly toward the cost of your new roof.
- Immediate Project Start: You don’t have to wait to save up the full amount. If your roof is leaking or damaged, you can get it replaced immediately, preventing further costly damage to your home.
- Fixed Budget: Knowing you have a specific deadline and amount to pay can help you create a disciplined budget to ensure the loan is paid off on time.
Disadvantages:
- Strict Payoff Deadlines: Missing the deadline by even a day or being a dollar short can trigger all the deferred interest. This means you could end up paying significantly more than anticipated.
- High Retroactive Interest: The interest rate applied retroactively is often quite high, sometimes 20% or more. This can quickly inflate your total cost.
- Higher Monthly Payments: To ensure you pay off the loan within the promotional period, your actual monthly payments will likely be much higher than any minimums offered by the lender.
- Potential for Hidden Fees: Always scrutinize the agreement for any application fees, annual fees, or other charges that might add to your cost.
Let’s look at an example. Imagine a $10,000 roof replacement.
| Scenario | Total Paid (On Time) | Total Paid (1 Day Late/Partial) |
|---|---|---|
| 0% Financing for 12 Months | $10,000 | $10,000 + ~24% APR = $12,400 |
This table is illustrative. The actual retroactive APR can vary significantly.
Who Qualifies for 0% Interest Roof Financing?
Qualifying for 0 roof financing isn’t always easy. Lenders offering these types of promotional deals typically look for homeowners with strong credit profiles. Generally, you’ll need a good to excellent credit score, often 700 or higher, to be approved. This helps lenders mitigate their risk, as they are essentially fronting the money with the hope (for them) that some borrowers will miss the deadline.
Beyond your credit score, lenders will also consider:
- Income Verification: You’ll need to demonstrate a stable and sufficient income to show you can handle the payments, especially if you plan to pay off the loan aggressively within the promotional window.
- Debt-to-Income (DTI) Ratio: Your DTI ratio, which compares your monthly debt payments to your gross monthly income, is another key factor. A lower DTI generally indicates you have more disposable income to manage new debt.
- Loan Amount Limits: Lenders may have limits on the maximum amount they’ll finance under a 0 roof financing promotion, which could impact whether it covers your entire roof replacement project.
- Lender-Specific Criteria: Each lender has its own set of rules, so what one approves, another might decline.
For more detailed information on paying for your roof, even if 0 roof financing isn’t the right fit, check out our guide on how to pay for a roof with no money. We believe every homeowner in our service areas like Katy, Spring, and Tomball deserves a safe and secure roof.
Smart Alternatives and Final Considerations
Choosing how to pay for a new roof is a significant decision. It’s about more than just the immediate cost; it’s about evaluating your financial situation, understanding the long-term affordability, and choosing the path that’s right for your family. We want you to make an informed decision that brings peace of mind, not financial stress.
What If You Don’t Qualify or Want Other Options?
If 0 roof financing doesn’t align with your financial goals or you don’t meet the stringent credit requirements, don’t despair! There are several other excellent alternatives available that we help our clients explore regularly.
- Personal Loans: These are unsecured loans, meaning they don’t require collateral like your home. They’re often approved quickly, sometimes in as little as 24 hours, making them a good option for urgent repairs. Interest rates for personal loans can vary widely, from around 6% to 36%, depending on your credit score and the lender. While they typically have higher interest rates than secured loans, they offer predictable, fixed monthly payments.
- Home Equity Lines of Credit (HELOCs): If you have equity in your home in areas like Richmond, Texas, or Pecan Grove, a HELOC can be a flexible option. It functions like a revolving credit line, allowing you to borrow funds as needed up to a certain limit, pay it back, and borrow again. HELOCs often have lower interest rates than personal loans because your home serves as collateral. However, interest rates are typically variable, meaning your monthly payment could fluctuate.
- FHA Title 1 Loans: These are government-backed loans specifically designed for home improvements. For loans up to $7,500, they are typically unsecured. For amounts over $7,500, they usually require your home to be collateral. FHA Title 1 loans have fixed interest rates and can be a good option for homeowners who might not have significant home equity or higher credit scores. You can learn more about these on the U.S. Department of Housing and Urban Development (HUD) website.
- Contractor Financing (Non-Promotional): Many roofing companies, including Reliable Roofing & Restoration, offer various financing plans through trusted partners that aren’t necessarily 0% deferred interest. These might include fixed-rate loans with competitive APRs and longer repayment terms (e.g., 60 or 120 months), leading to lower, more manageable monthly payments. For example, a $10,000 loan at 9.99% for 120 months could result in a monthly payment around $132. While you’ll pay interest over time, these plans offer predictability and can be a better fit if you prefer consistent payments without the pressure of a short-term, interest-free deadline.
We offer a range of solutions to help you find the best fit for your budget. Explore all your possibilities on our Roofing Financing Options page.
Key Questions to Ask Before Signing Any Financing Agreement
Before you sign on the dotted line for any financing option, especially 0 roof financing, it’s crucial to ask thorough questions and understand every detail. We encourage our clients in Brookshire, Pattison, and Simonton to be their own best advocates. Here’s a list of critical questions:
- What is the Annual Percentage Rate (APR) after the promotional period ends? This is vital for deferred interest loans. If you don’t pay it off on time, this is the rate that will be applied retroactively.
- Is there a deferred interest clause? If so, confirm exactly how it works. Understand if all accrued interest is added back, or only on the remaining balance. Most 0% offers are indeed deferred interest.
- Are there any prepayment penalties? You want the flexibility to pay off the loan early without incurring extra fees, especially if you’re aiming for that 0% window.
- What are all the associated fees? Ask about application fees, origination fees, annual fees, or any other hidden charges that might increase the total cost.
- What is the total cost of the loan if you pay it off over the full term (including interest and fees)? This gives you a clear picture of the maximum you might pay.
- What are the minimum monthly payments, and what monthly payment is required to pay off the loan before the promotional period ends? Make sure you understand the difference and can commit to the higher payment if necessary.
- What credit bureaus does the lender use for their credit check? Is it a hard or soft pull? A soft pull won’t impact your credit score, while a hard pull will.
- How long is the loan term after the promotional period? Knowing this helps you understand the long-term commitment if you don’t meet the 0% deadline.
Is 0% Roof Financing the Right Choice for Your Katy Home?
Whether 0 roof financing is the right choice for your home in Katy, Richmond, Spring, or any of our surrounding service areas comes down to your personal financial situation and discipline.
- It’s a good option if: You have a clear plan and the financial means to pay off the entire loan balance within the promotional period. This could be from a planned bonus, savings, or an insurance settlement (not for the roof itself). You have an excellent credit score, ensuring you qualify for the best terms. You want to avoid paying any interest at all.
- It’s a risky option if: Your financial situation is uncertain, or you’re not confident you can pay off the full amount before the deadline. If you anticipate any unexpected expenses that might prevent you from making aggressive payments, the retroactive interest can be a severe financial blow.
Considering the unpredictable Texas climate, with its intense heat, humidity, and severe weather events, timely roof replacement is not just about aesthetics; it’s about protecting your biggest asset. A compromised roof in Spring, Katy, or Missouri City can quickly lead to bigger problems. According to a 2017 Remodeling Magazine report, roofing replacement adds, on average, roughly $14,000 to your home’s value, making it a worthwhile investment that often recoups its cost. This means a new roof not only protects your home but also improves its marketability and value.
At Reliable Roofing & Restoration, we are committed to helping you steer these decisions. We offer competitive financing options and can help you determine if 0 roof financing or another plan is the best fit for your needs. Don’t let financial concerns delay essential home protection. Your home deserves a reliable roof, and we’re here to help make it happen. Learn more about your Roof Replacement Financing Options with us.