Roof replacement insurance claim: 7 Powerful Tips for Success 2025
Why Understanding Your Roof Replacement Insurance Claim Matters
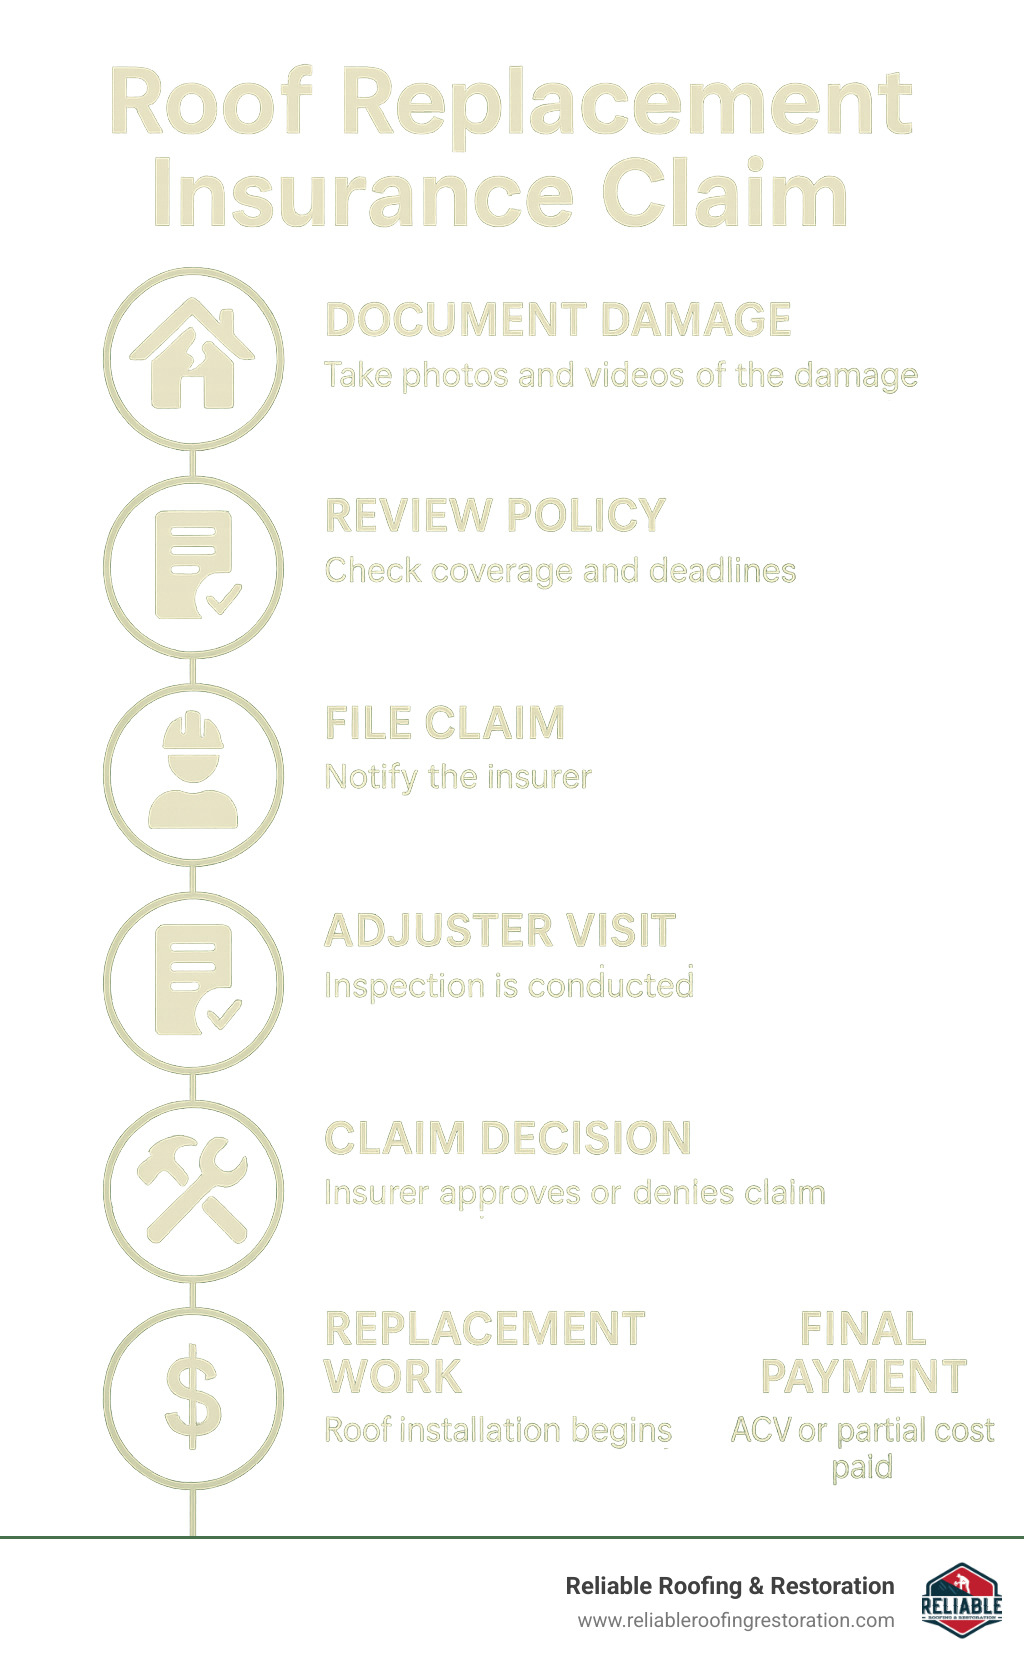
Roof replacement insurance claim processes can feel overwhelming when you’re dealing with storm damage and need answers fast. Here’s what you need to know:
Key Steps for Your Claim:
• Document damage immediately – Take photos and videos from multiple angles
• Review your policy – Check if you have ACV (Actual Cash Value) or RCV (Replacement Cost Value)
• File promptly – Florida requires notification within 10 days under SB 76
• Meet your deductible – Typically 2% of home value inland, 5% coastal
• Work with adjusters – Have your contractor present during inspections
What’s Usually Covered:
• Wind and hail damage from storms
• Fire and lightning strikes
• Fallen trees or debris
What’s NOT Covered:
• Normal wear and tear
• Lack of maintenance
• Flood damage (needs separate policy)
Florida homeowners face unique challenges with roof claims. The state endures an average of six tropical storms and hurricanes each year, while home insurance rates run four times the national average. Recent legislation like SB 4-D has also changed the traditional 25% roof replacement rule, affecting how partial repairs versus full replacements are handled.
I’m David Shepherd, and I’ve spent years helping Texas homeowners steer storm damage assessments and insurance claim processes at Reliable Roofing & Restoration. My experience with roof replacement insurance claim coordination has shown me how proper documentation and understanding your policy can make the difference between a smooth process and months of delays.
Simple guide to Roof replacement insurance claim:
– Asphalt shingle roof replacement
– Asphalt shingle roof warranty
– Free roof replacement quote
Roof Replacement Insurance Claim Essentials
When you’re dealing with a damaged roof, understanding how your roof replacement insurance claim works can save you thousands of dollars and weeks of stress. Let me walk you through the key elements that determine whether your claim gets approved and how much you’ll receive.
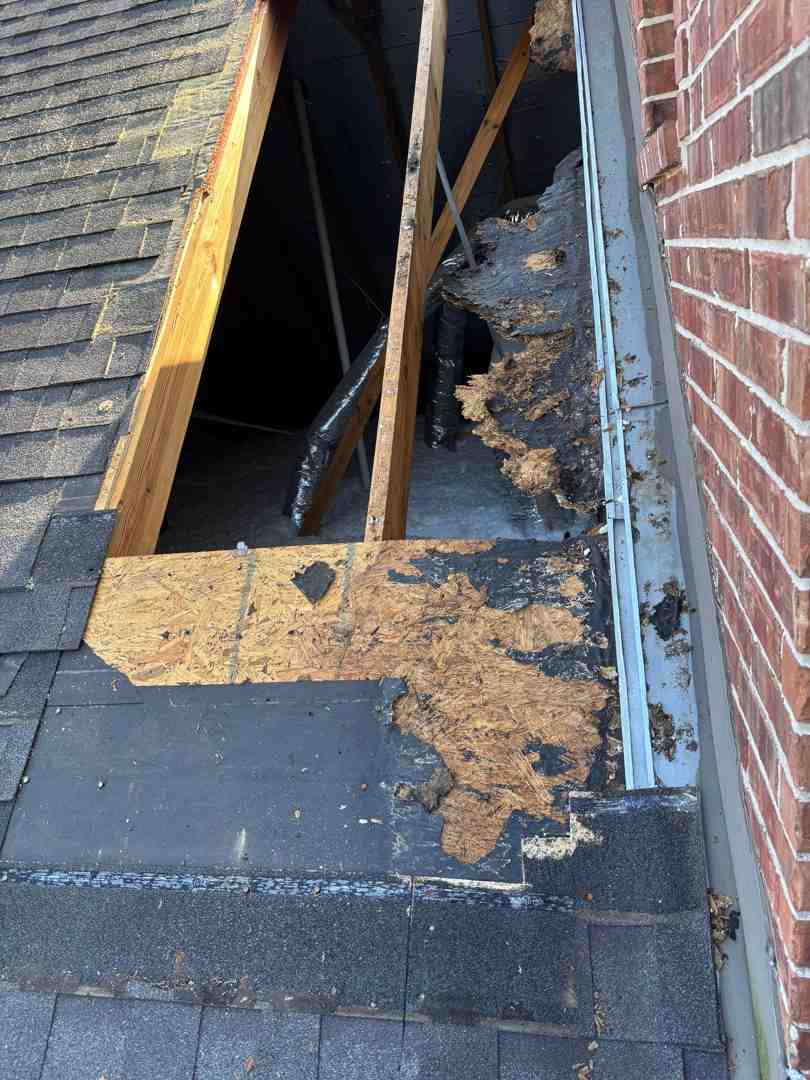
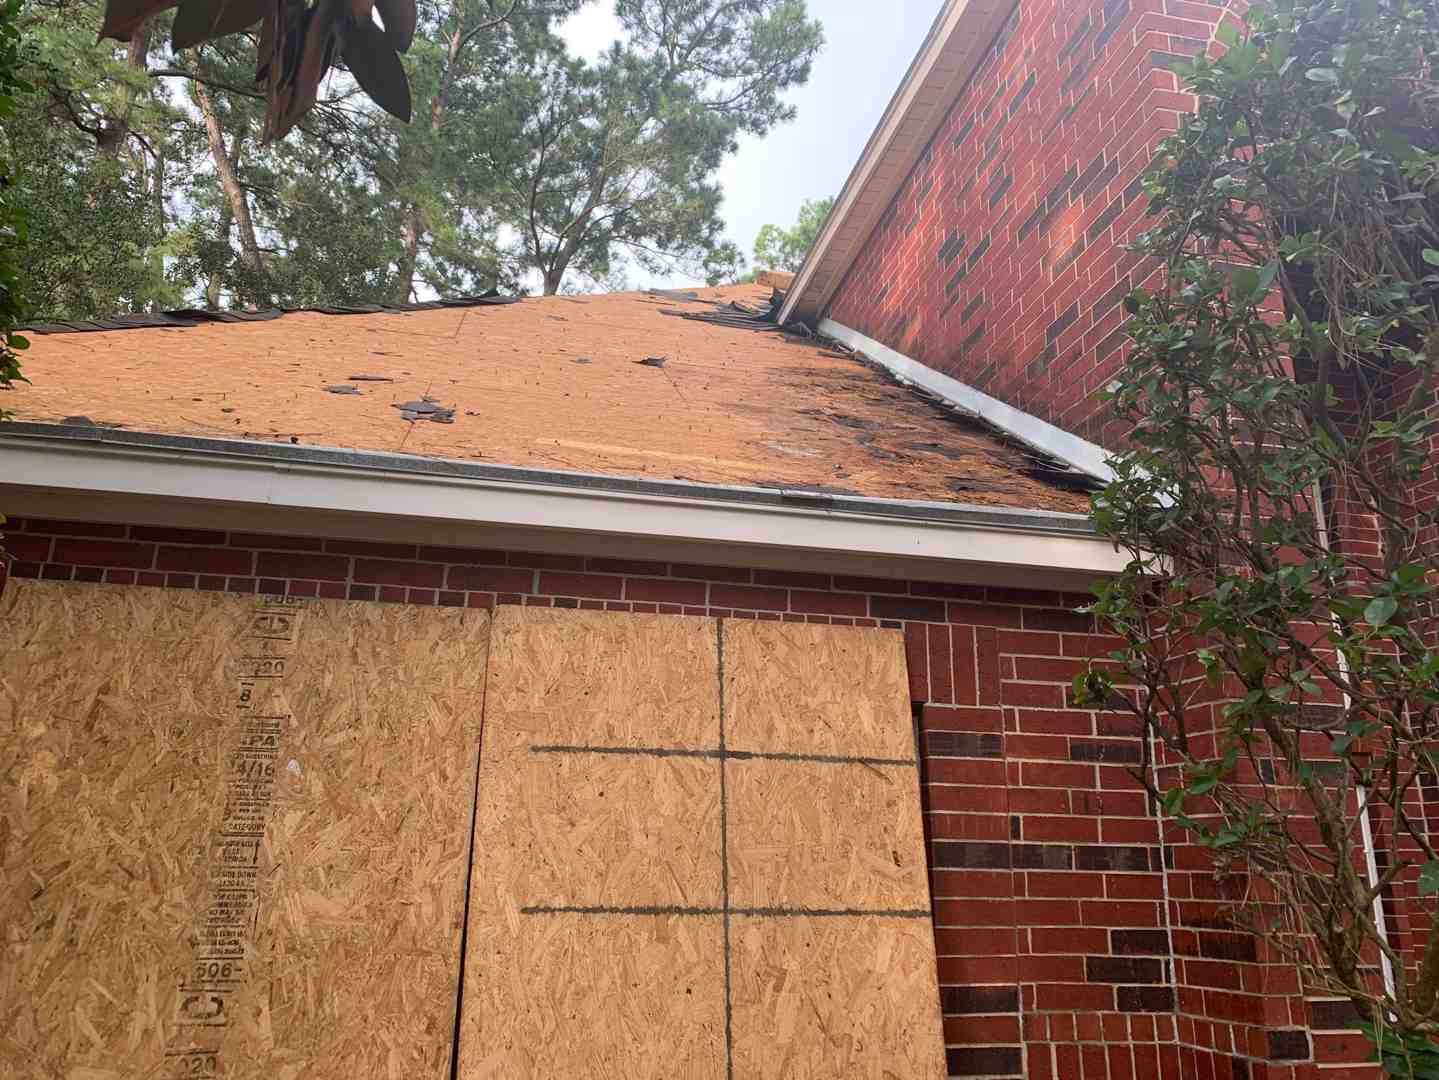
Most homeowners policies cover sudden, accidental damage – but the specifics matter more than you might think. Wind damage from hurricanes and severe storms causes the majority of roof claims we see. When wind speeds exceed what your roof was designed to handle, you’ll notice missing shingles, exposed underlayment, and sometimes damage to the wooden decking underneath.
Hail damage creates a completely different pattern. Instead of missing pieces, you’ll see granule loss on asphalt shingles, small cracks or punctures, and often dented gutters, vents, or flashing. Even small hail can cause significant damage that isn’t immediately visible from the ground.
Fire damage from lightning strikes or other causes typically receives the most comprehensive coverage. Unlike wind or hail damage that might qualify for partial repairs, fire often requires complete roof replacement, which insurance companies generally cover without much dispute.
Your deductible plays a huge role in your out-of-pocket costs. In Texas, most policies carry deductibles of 2% of your home’s insured value for inland properties. Coastal areas often see 5% deductibles due to hurricane risk. That means on a $300,000 home, you’d pay $6,000 before insurance coverage kicks in inland, or $15,000 if you’re near the coast.
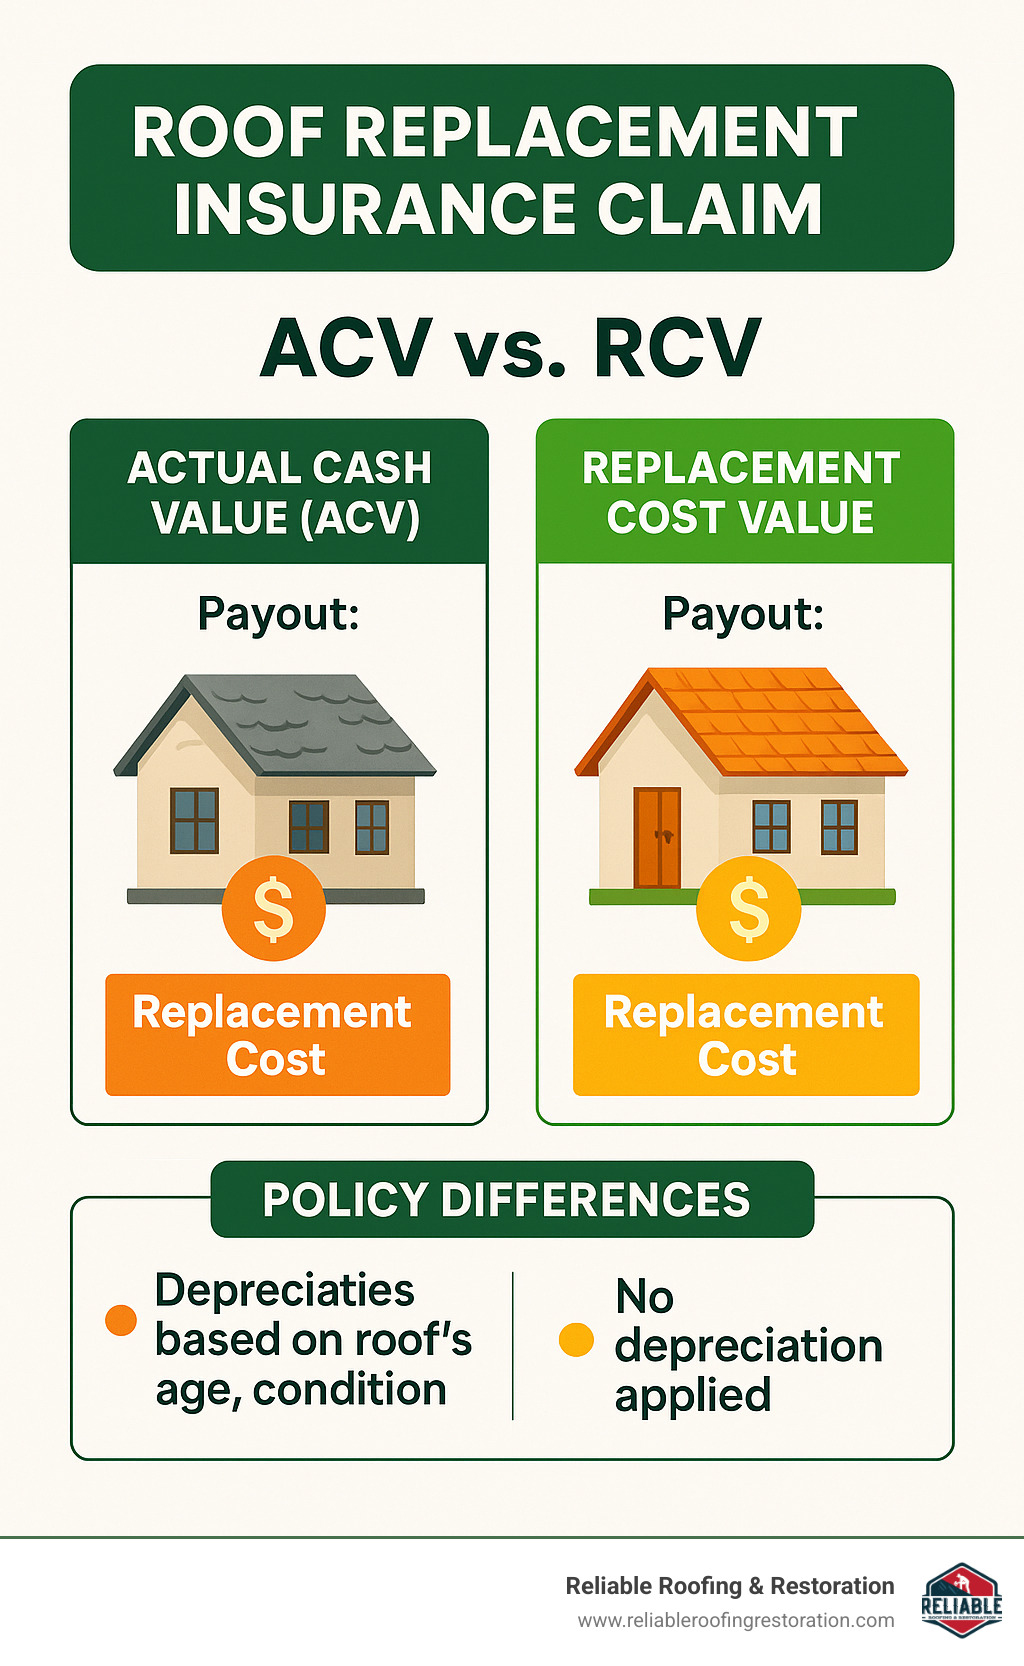
The age and condition of your roof dramatically affect your claim outcome. Insurance companies use depreciation schedules that reduce payouts as roofs get older. A 15-year-old asphalt shingle roof might only receive 50% of replacement cost under an Actual Cash Value policy, while a Replacement Cost Value policy covers the full amount minus your deductible.
In Florida, building codes have a 25% rule that traditionally required full roof replacement when 25% or more of the roof area needed repair within 12 months. Recent legislation under SB 4-D has modified this requirement for newer homes, which can significantly impact whether you get a partial repair or full replacement.
Florida’s Valued Policy Law provides extra protection when your roof is completely destroyed. If multiple causes contribute to a total loss and at least one is covered by your policy, insurers must pay the full policy limit regardless of what specifically caused each part of the damage.
Covered vs Non-Covered Roof Damage
Understanding what your insurance will and won’t cover can save you from unpleasant surprises when filing your roof replacement insurance claim. Storm-related damage forms the foundation of most roof coverage, but the details matter.
Wind damage from hurricanes, tornadoes, and severe thunderstorms typically receives full coverage when it exceeds your roof’s design limits. Hail damage qualifies for coverage regardless of the hail size, as long as it causes actual functional damage to your roofing system.
Fire damage gets comprehensive coverage under most policies, whether the fire starts from a lightning strike, electrical problem, or spreads from elsewhere. Even if a neighbor’s fire spreads to your roof, your homeowners policy should respond.
However, wear and tear exclusions eliminate coverage for gradual deterioration. If your 20-year-old shingles are curling and cracking from normal aging, insurance won’t pay for replacement. Maintenance neglect can also void coverage – failing to replace missing shingles or clean gutters can leave you responsible for resulting damage.
Flood exclusions represent a major gap in standard homeowners coverage. Water damage from storm surge, rising rivers, or surface flooding requires separate flood insurance. The good news? Rain entering through storm-damaged openings in your roof typically gets covered under your standard policy.
How Roof Age & Condition Influence a Roof Replacement Insurance Claim
The relationship between your roof’s age and insurance coverage follows predictable patterns that can significantly impact your claim payout. Most asphalt shingle roofs last 20-30 years, while premium materials like metal or tile can protect your home for 50+ years.
Insurance companies apply depreciation schedules that reduce claim payouts as roofs age. A typical schedule might depreciate asphalt shingles at 5% per year after the first five years. This means a 15-year-old roof could face 50% depreciation under an Actual Cash Value policy.
Material type significantly influences both lifespan and insurance treatment. From our experience, 3-tab asphalt shingles last 20-22 years on average, while dimensional asphalt shingles extend to 25-28 years. Premium materials like cedar shake can reach 30 years in favorable climates, while slate roofing can last 50-125 years depending on the grade.
Keeping regular inspection records helps demonstrate proper maintenance and strengthens your claim when damage occurs. We recommend annual professional inspections, especially for roofs over 10 years old. These records prove you’ve maintained your roof properly and help distinguish legitimate storm damage from normal wear and tear.
ACV vs RCV Payouts for Your Roof Replacement Insurance Claim
The difference between Actual Cash Value and Replacement Cost Value policies can mean thousands of dollars when you’re filing a roof replacement insurance claim. Understanding these policy types helps set realistic expectations for your claim outcome.
ACV policies pay the depreciated value of your roof at the time of loss. If your roof cost $15,000 new but has depreciated 40% over its lifetime, you’d receive $9,000 minus your deductible. This often leaves homeowners covering significant out-of-pocket expenses for full replacement.
RCV policies cover the full cost to replace your roof with similar materials, minus your deductible. However, most RCV policies use a two-payment system. You receive the depreciated value initially, then the remaining “recoverable depreciation” after completing repairs and submitting proof of payment.
Here’s how the numbers work on a $15,000 roof replacement with 40% depreciation and a $2,000 deductible. An ACV policy pays $7,000 total, while an RCV policy pays $13,000 total. The payment schedule for RCV policies typically releases the ACV amount ($7,000) after claim approval, then the recoverable depreciation ($6,000) once you complete repairs and submit your contractor’s invoice.
Florida’s 25% Rule, SB 4-D & Other Key Laws
Florida’s building code traditionally required full roof replacement when 25% or more of a roof section needed repair within 12 months. This rule applied to the total roof area, including decking, underlayment, and surface materials – not just the visible shingles you see from the ground.
Senate Bill 4-D, effective July 2021, modified this requirement for homes built or re-roofed after March 1, 2009. Properties meeting current building code standards can now pursue partial repairs even when damage exceeds 25% of a roof section, provided the repairs meet current code requirements.
This change significantly impacts insurance claims because it allows insurers to approve partial repairs instead of full replacements in many cases. For homeowners, this typically means faster repairs but potentially less comprehensive coverage than you might have received under the old rule.
Florida’s Valued Policy Law provides additional protection for total losses. When your roof suffers complete destruction and multiple causes contributed to the loss, insurers must pay the full policy limit if at least one covered event played a role. This law doesn’t apply to partial losses except in fire claims.
Recent legislation also established strict notification requirements under SB 76. Homeowners must notify their insurance company within 10 days of finding damage. Missing this deadline can complicate or potentially invalidate your claim, so document and report damage promptly after any storm event.
Step-by-Step Guide: From Damage Findy to Roof Restoration

When storm clouds clear and you step outside to assess the damage, that first moment of findy sets everything in motion. I’ve walked countless homeowners through this exact scenario, and I can tell you that what happens in those first 48 hours often makes or breaks your roof replacement insurance claim.
Your safety comes first, always. Resist the urge to climb up and inspect your roof personally – that’s what we professionals are for. Instead, walk around your property from ground level and look for the obvious signs. Missing shingles scattered across your yard tell a story. Dented gutters, damaged vents, or visible holes in your roofing all point to storm damage that needs immediate attention.
Temporary protection becomes your next priority. If you can see exposed areas where rain might enter, get them covered with tarps right away. Keep every receipt for materials and any emergency labor you hire – most policies reimburse these costs without counting them toward your deductible. Think of it as insurance protecting your insurance claim.
Photo documentation needs to be thorough and systematic. Take wide shots that show your entire roof, then zoom in for close-ups of specific damage. Include something for scale – a coin, ruler, or even your hand works perfectly. Video can capture subtle details that photos miss, especially things like granule loss that might not show up clearly in still images.
Contact your insurance company within their required timeframe. In Florida, you have 10 days to report damage, though getting it done sooner always works in your favor. When you call, ask for your claim number immediately and write it down. You’ll reference this number in every future conversation.
Here’s where having a professional inspection before your adjuster arrives makes all the difference. We’ve seen too many cases where subtle damage gets missed during the initial assessment. Having detailed contractor documentation strengthens your position and ensures nothing important gets overlooked.
Deductible timing often confuses homeowners. You won’t write a check to your insurance company – instead, you’ll pay your deductible directly to your contractor. The insurance company simply reduces their payment by your deductible amount, so the math works out perfectly.
Most roof replacement insurance claims follow a predictable timeline. You’ll typically wait one to two weeks for adjuster scheduling, another week or two for the actual visit and assessment, then two to four weeks for claim approval and your first payment. Final payments usually process within one to three weeks after work completion.
Does Insurance Cover Roof Replacement? dives deeper into coverage specifics and requirements that might affect your particular situation.
Documentation Required for a Successful Roof Replacement Insurance Claim
Building a comprehensive claim file feels like detective work, but it’s detective work that pays off when your roof replacement insurance claim gets processed. Every piece of documentation tells part of your story, and insurance companies respond better to complete stories.
Before-and-after photo comparisons provide some of the most compelling evidence you can submit. If you happen to have photos of your roof from before the storm – maybe from a real estate listing or home improvement project – include them in your file. Take new photos from similar angles to show the contrast clearly.
Video documentation captures movement and details that static photos simply can’t convey. Walk around your property while recording, narrating what you’re seeing as you go. Focus on areas where shingles are missing or displaced, and don’t forget to film any debris in your yard that clearly came from your roof.
Written records should include when you first noticed the damage, what the weather was like during the storm, and any immediate steps you took to protect your property. Note specific dates, times, and detailed observations about each damaged area you identify.
Professional contractor inspection reports add credibility that insurance companies respect. We provide detailed assessments that identify all storm-related damage, clearly distinguish it from normal wear and tear, and specify exactly what repairs or replacement work is needed.
Receipt management becomes crucial for maximizing your reimbursement. Keep everything related to your claim – emergency repairs, temporary housing costs if needed, and any materials you buy for protection. These expenses are often fully reimbursable and don’t count toward your deductible.
Communication logs help you track progress and ensure nothing falls through the cracks. Write down every phone call, email, and meeting with your insurance company. Include dates, times, and the names of everyone you speak with. This simple step prevents misunderstandings and keeps your claim moving forward.
Filing, Adjuster Visit, Payout & Deductible Basics
The moment you contact your insurance company, your claim officially begins. Have your policy number ready, along with the date when damage occurred and a brief description of what happened. The company will assign you a claim number – treat this number like gold and reference it in every future conversation.
Most insurers now offer multiple ways to file claims. You can call, use their website, or download their mobile app. Choose whichever method makes it easiest for you to submit photos and documentation. Some companies provide claim numbers immediately, while others take up to 48 hours to process your initial filing.
Adjuster scheduling typically happens within a few days, though major storms can create delays across entire regions. When you schedule the appointment, specifically request that your roofing contractor be present during the inspection. This ensures all damage gets properly identified and documented.
During the adjuster’s visit, walk through everything systematically. Start with the most obvious exterior damage, then show any interior effects like water stains or active leaks. Point out areas your contractor identified that might not be immediately visible to someone who doesn’t climb roofs professionally.
Your adjuster will create a scope of loss document that details all covered damage and estimated repair costs. Review this carefully and ask questions about anything that seems missing or inadequately addressed. Most adjusters appreciate input from qualified contractors who know local building requirements.
First payment timing varies depending on your insurance company and how complex your claim turns out to be. Simple, straightforward claims might receive payment within a week of the adjuster visit. More complex cases can take several weeks to process. This initial payment typically covers the actual cash value amount minus your deductible.
Final payment processing happens after you submit proof that work has been completed along with final invoices from your contractor. This releases any recoverable depreciation if you have replacement cost coverage. Most insurance companies process these final payments within one to two weeks of receiving proper documentation.
For homeowners in our service areas including Katy, Sugar Land, Houston, and surrounding communities, we coordinate closely with insurance adjusters to keep everything moving smoothly. Our experience with local building codes and insurance requirements helps streamline the entire process from initial damage assessment through final payment.
Pricing for roof replacement depends heavily on your roof’s pitch, waste factors, and material selection. Your average asphalt shingle replacement costs $300-$450 per square, though these numbers can vary significantly based on your specific situation. We provide detailed estimates that break down all costs clearly for both you and your insurance adjuster.
More info about roofing services — Reliable Roofing & Restoration offers comprehensive support throughout your roof replacement insurance claim process, from initial documentation through final restoration.
Most home insurance policies require claims to be filed within two years of the damage date, though immediate notification always provides better outcomes. The combination of proper documentation, professional contractor support, and clear communication with your insurer creates the foundation for successful claim resolution and quality roof restoration.