Roofing Financing Options: 7 Best Smart Choices 2024
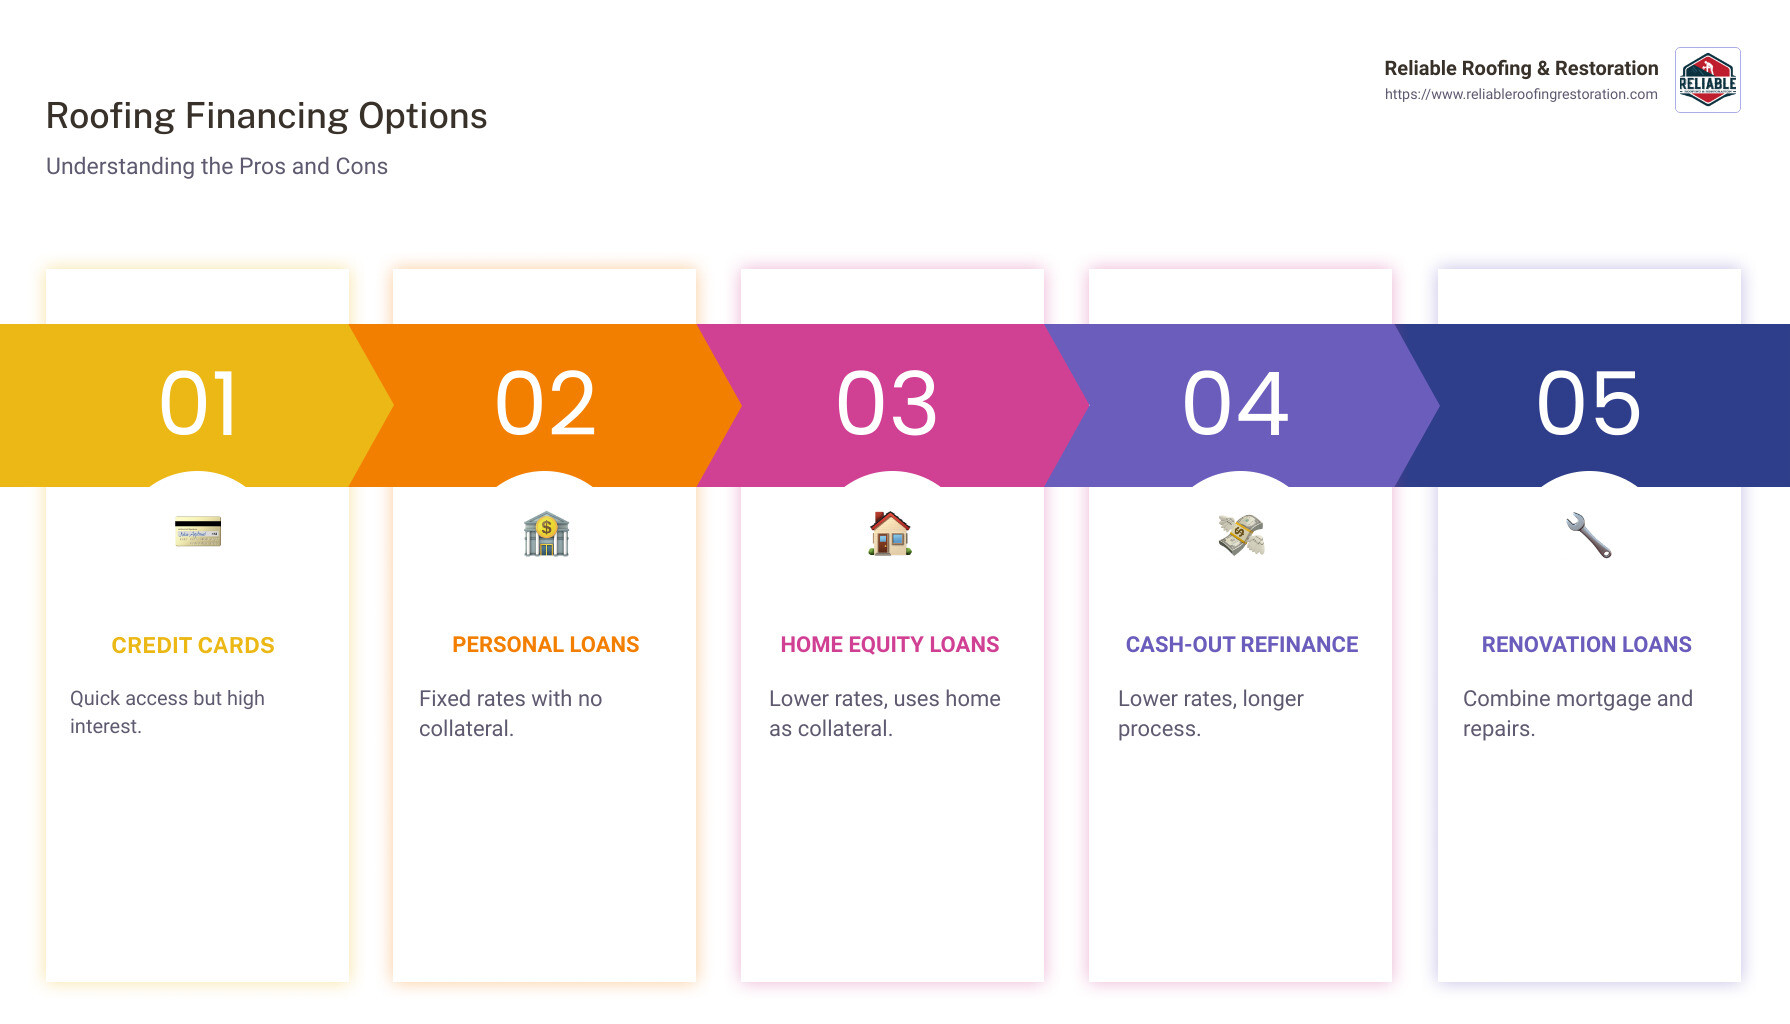
When you’re faced with a necessary roof replacement, understanding your roofing financing options is crucial to manage the costs effectively. Whether your roof is nearing the end of its life or you’re dealing with an unexpected leak, finding the right financing strategy can make a significant difference. Here’s a quick overview of the roofing financing options you may consider:
- Credit Cards – Quick access to funds but high interest rates.
- Personal Loans – Fixed rates without risking your home.
- Home Equity Loans – Lower rates but slower to obtain.
- HELOC (Home Equity Line of Credit) – Flexibility with potential home risk.
- Cash-Out Refinance – Lower rates with longer funding process.
- Renovation Loans – Combine mortgage and repairs with complex terms.
- Roof Contractor Financing – Easy approval and possible interest-free terms.
My name is David Shepherd, and I bring years of experience in storm damage assessment and roofing project oversight, ensuring superior results for clients at Reliable Roofing & Restoration. My expertise in roofing financing options helps homeowners seamlessly steer their roofing needs with minimal financial strain.
Basic roofing financing options vocab:
– roof replacement financing
– roof replacement financing options
Understanding Roofing Financing Options
Navigating roofing financing options can seem daunting, but breaking them down into key factors like credit score requirements, loan types, and interest rates can simplify the process.
Credit Score Requirements
Your credit score is a major factor in determining which financing options are available to you. For example, if you have a lower credit score, you might qualify for an FHA 203(k) loan, which requires a minimum score of 500 with a 10% down payment. On the other hand, a Fannie Mae HomeStyle® renovation loan typically requires a score of at least 620.
Knowing your credit score can help you focus on the options that are right for you and avoid unnecessary credit inquiries.
Loan Types
There are several types of loans you can consider for roofing projects. Here’s a quick look:
-
Credit Cards: Useful for quick roof repairs. They offer fast funding but often come with high APRs, which can make them expensive if not paid off quickly.
-
Personal Loans: These loans provide a lump sum with fixed monthly payments and rates. They don’t require collateral, so you won’t risk losing your home if you default.
-
Home Equity Loans and HELOCs: These options leverage your home’s equity. They generally offer lower interest rates but can take longer to secure. Be cautious, as they put your home at risk if you default.
-
Cash-Out Refinance: This option allows you to refinance your mortgage for more than you owe and take the difference in cash. It often comes with lower rates and tax benefits but has a longer funding time.
-
Renovation Loans: Loans like the FHA 203(k) and HomeStyle® allow you to combine your mortgage and renovation costs. They provide higher borrowing power but involve more complex approval processes.
-
Roof Contractor Financing: Offered directly through some roofing companies, these options can be easy to get and may offer interest-free terms for good-credit borrowers. However, they might include potential liens on your home.
Interest Rates
Interest rates vary widely across different roofing financing options. Personal loans and credit cards often have higher rates compared to home equity loans or cash-out refinances. For instance, personal loans can range from 7% to 36%, depending on your credit score and lender.
It’s crucial to compare rates and terms to find the most affordable option for your situation. That while lower rates can save you money over time, higher rates might be worthwhile if they offer faster access to funds for urgent repairs.
Understanding these factors will help you make an informed decision and choose the best financing option for your roofing needs.
7 Roofing Financing Options to Consider
When it comes to roofing financing options, it’s crucial to weigh the pros and cons of each to find the best fit for your needs and financial situation. Here’s a breakdown of seven popular options:
1. Credit Cards
Pros:
– Quick access to funds.
– Potential for 0% APR promotional periods.
Cons:
– High variable interest rates, often around 24.37%.
– Can become expensive if not paid off quickly.
Credit cards are a viable choice for immediate repairs, especially if you can pay off the balance during a 0% APR period. However, they should be used cautiously due to high interest rates.
2. Personal Loans
Pros:
– Fixed rates and predictable payments.
– No collateral required, so no risk of losing your home.
Cons:
– Higher rates than home equity options.
– Shorter terms, which may mean higher monthly payments.
Personal loans provide a lump sum and can be a good choice if you want to avoid using your home as collateral. They offer quick funding, often within a day.
3. Home Equity Loans and HELOCs
Pros:
– Lower interest rates than personal loans.
– Interest may be tax-deductible.
Cons:
– Longer approval and funding process.
– Risk of foreclosure if you default.
These options leverage your home equity and can offer significant savings on interest. However, they come with the risk of losing your home if payments are missed.
4. Cash-Out Refinance
Pros:
– Typically lower interest rates.
– Tax benefits on interest.
Cons:
– Longer funding time and higher closing costs.
– Risk of foreclosure if you default.
This option allows you to refinance your existing mortgage and take out cash for your roofing needs. It’s ideal for those who want to combine mortgage and roofing costs.
5. Renovation Loans
Pros:
– Combine roofing and mortgage costs.
– Higher borrowing power based on post-renovation home value.
Cons:
– Complex approval process.
– Higher upfront costs.
Renovation loans like the FHA 203(k) offer a way to finance extensive repairs or upgrades, but require more paperwork and planning.
6. Roof Contractor Financing
Pros:
– Easy approval process.
– Interest-free options for borrowers with good credit.
Cons:
– Potential for higher interest rates.
– Possible lien on your home.
Some roofing companies provide financing directly, which can be convenient. However, it’s important to read the terms carefully to avoid unexpected costs.
7. Insurance Claims
Pros:
– May cover full replacement in cases of storm damage.
– Can reduce out-of-pocket expenses.
Cons:
– Policies often exclude wear and tear.
– Coverage may not be comprehensive.
If your roof damage is due to a covered event, insurance can be a significant help. Be sure to review your policy details and start a claim promptly.
Choosing the right roofing financing option involves considering your credit score, urgency of the repair, and long-term financial impact. Each option has unique benefits and drawbacks, so it’s important to evaluate them in the context of your specific situation.
Credit Cards for Roofing
When it comes to roofing financing options, credit cards can offer a swift solution. They provide quick access to funds, which is especially useful in emergencies when your roof needs immediate attention. If you have a good credit score, you might be eligible for a credit card with a 0% APR introductory offer, typically lasting 12 to 18 months. This can allow you to finance your roofing repairs interest-free, as long as you pay off the balance within the promotional period.
However, while the speed and convenience of credit cards are appealing, there are significant downsides to consider. High APRs are a major concern. Recent data shows that average APRs on new credit cards have reached 24.37%, the highest since 2019. This means if you don’t clear your balance during the 0% APR period, your debt could quickly become expensive.
Another factor to consider is the variable interest rates associated with credit cards. Unlike some fixed-rate loans, credit card rates can fluctuate, potentially increasing your costs over time. This unpredictability can make budgeting for repayments more challenging.
If the cost of your roof repair is on the lower end and you can manage to pay it off quickly, a credit card might be a suitable option. Just ensure you’re aware of any potential transaction fees that might be charged by your roofer for credit card payments.
While credit cards can be a viable short-term solution, they should be used cautiously. The high-interest rates and variable terms can make them one of the more expensive options if not managed carefully. Always weigh the urgency of your roofing needs against the long-term financial impact.
Personal Loans for Roofing
When considering roofing financing options, personal loans stand out as a practical choice for many homeowners. They offer a blend of convenience, speed, and security that can make them an attractive option for funding roof repairs or replacements.
Fixed Rates: One of the main advantages of personal loans is their fixed interest rates. This means your monthly payments remain the same throughout the loan term, making it easier to budget and plan your finances. Unlike credit cards, where rates can fluctuate, personal loans provide a predictable repayment schedule.
No Collateral Required: Personal loans are unsecured, meaning you don’t have to put your home or any other asset at risk. This is a significant benefit if you prefer not to tie your property to your borrowing. You can secure funds without the anxiety of potentially losing your home if you encounter financial difficulties.
Quick Funding: Speed is another key advantage of personal loans. Many lenders can provide funds within a day or two, making this option suitable for urgent roofing needs. This rapid access to cash can be crucial if you’re dealing with a leaky roof or other pressing issues that require immediate attention.
However, it’s important to weigh these benefits against some of the downsides. Personal loans can have higher interest rates than home equity options, and the terms are usually shorter. This means you might end up with higher monthly payments compared to other financing methods.
In summary, personal loans offer a reliable, no-collateral-needed solution with fixed rates and quick access to funds. They’re particularly useful if you need a set amount of money quickly and prefer a predictable repayment plan. Just be sure to shop around for the best rates and terms to suit your financial situation.
Home Equity Loans and HELOCs
When it comes to roofing financing options, tapping into your home equity can be a powerful tool. Both Home Equity Loans and Home Equity Lines of Credit (HELOCs) allow you to borrow against the equity you’ve built up in your home. Let’s break down the benefits and risks of these options.
Tax-Deductible Interest: One of the standout features of home equity loans and HELOCs is the potential tax benefit. The interest you pay on these loans may be tax-deductible if the funds are used for home improvements, including roof repairs. This can make them more cost-effective compared to other borrowing methods. However, it’s wise to consult a tax professional to understand how this applies to your situation.
Home Equity as Collateral: Both options use your home as collateral, which means they often come with lower interest rates than unsecured loans like personal loans or credit cards. This can result in lower monthly payments and overall costs. However, the amount you can borrow is typically limited to a percentage of your home equity, which is the difference between your home’s market value and what you owe on your mortgage.
Risk of Foreclosure: The major downside to consider is the risk of foreclosure. Since your home is the collateral, failing to make payments could lead to losing your home. It’s crucial to borrow only what you can comfortably repay and to have a solid plan for managing the loan.
A Home Equity Loan provides a lump sum with a fixed interest rate, making it ideal for homeowners who prefer a predictable monthly payment. On the other hand, a HELOC offers flexibility, allowing you to draw funds as needed during the draw period, like a credit card. This is useful for ongoing or unexpected roofing projects.
In summary, home equity loans and HELOCs offer competitive interest rates and potential tax benefits, making them attractive for those with significant home equity. However, the risk of foreclosure necessitates careful planning and consideration. Always evaluate your ability to repay before committing to these options.
Cash-Out Refinance
A cash-out refinance is a popular choice for homeowners looking to finance roofing projects. This option involves replacing your existing mortgage with a new one that has a higher loan amount. The difference in cash can be used for your roofing needs. Let’s explore why this might be an appealing option.
Lower Rates: One of the major advantages of a cash-out refinance is the potential for lower interest rates. Since these rates are typically lower than those of personal loans or credit cards, this can mean substantial savings over time. However, compare current mortgage rates with your existing rate to ensure you’re getting a better deal.
Tax Benefits: Another benefit is the potential for tax deductions. If the funds from the refinance are used for home improvements, like roof replacement, the interest on your new mortgage might be tax-deductible. This can make a cash-out refinance more financially attractive, but it’s always best to consult with a tax advisor to understand how these benefits apply to your situation.
Longer Funding Time: While the benefits are clear, a cash-out refinance isn’t the quickest option. The process can take longer than other financing methods, with average closing times around 47 days. This makes it less suitable for urgent roofing repairs but a viable choice if you have the luxury of time.
A cash-out refinance can be a cost-effective way to finance a new roof, thanks to its lower rates and tax advantages. However, the longer processing time requires careful planning. Make sure you weigh the pros and cons and consider your timing needs before proceeding with this option.
Renovation Loans
When considering roofing financing options, renovation loans like the FHA 203(k) and Fannie Mae HomeStyle can be powerful tools. These loans not only offer higher borrowing power but also the flexibility to wrap renovation costs into your mortgage.
FHA 203(k) Loan
The FHA 203(k) loan is a government-backed option designed to help homeowners finance both the purchase and renovation of a home. This loan is particularly beneficial if you plan to make significant improvements, such as a roof replacement.
-
Higher Borrowing Power: Unlike home equity loans or cash-out refinances, the FHA 203(k) loan is based on the projected value of your home after renovation. This means you can borrow more, enabling you to invest in quality materials or more extensive upgrades.
-
Lenient Credit Requirements: With credit score requirements as low as 500 (with at least 10% equity), this loan is accessible to many homeowners. However, if your roof repair costs exceed $35,000, you might need to work with an approved consultant.
-
Streamlined Process: The loan includes the cost of materials and labor for the renovation, and funds are disbursed as work progresses. This can simplify managing your roof project financially.
Fannie Mae HomeStyle Loan
The HomeStyle renovation loan from Fannie Mae is another excellent choice for those looking to improve their homes. This loan allows you to finance up to 97% of your home’s value, including roof repair costs.
-
Flexible Use: Like the FHA 203(k), the HomeStyle loan uses the future value of your home to determine borrowing limits. This gives you the flexibility to choose higher-end roofing materials without being constrained by your home’s current value.
-
Credit Score Requirement: You’ll need a minimum credit score of 620 to qualify. If you meet this requirement, you can enjoy competitive interest rates and potentially lower monthly payments.
-
Project Approval: Before the loan closes, your lender must approve your roofing contractor and project plans. This ensures that your renovation is feasible and aligns with the lender’s standards.
Renovation loans can be an excellent choice for homeowners looking to improve their property’s value and aesthetics. By leveraging these loans, you can tackle major projects like roof replacements with more financial confidence and flexibility.
Roof Contractor Financing
When exploring roofing financing options, roof contractor financing can be a practical choice for many homeowners. This option often provides easy approval, interest-free periods, and a direct line of communication between the homeowner and the contractor.
Easy Approval
Roof contractor financing typically offers a straightforward approval process. Many roofing companies partner with financing providers to offer plans that are easy to apply for, often requiring just a phone call or a simple online form. This convenience can be especially beneficial if you need to start your roofing project quickly and don’t want to wait for lengthy loan approvals.
Interest-Free Options
One of the attractive features of roof contractor financing is the possibility of interest-free periods. Some contractors offer promotional deals, such as six months with no interest or payments. However, it’s crucial to compare these offers with other financing options to ensure you’re not paying inflated costs elsewhere, such as hidden fees or higher service charges.
Potential Liens
While contractor financing is convenient, it’s essential to be aware of potential mechanics liens. A lien is a legal claim against your property if you fail to pay for the roofing services. To avoid this, ensure you have a clear payment plan and discuss lien releases with your contractor before the project begins. Once the work is completed and fully paid, request a lien release to protect your home’s title.
Roof contractor financing offers a blend of convenience and flexibility, making it a viable option for those who prefer to keep the financing process simple and directly tied to their roofing contractor.
By understanding the benefits and potential pitfalls, you can make a well-informed decision that aligns with your financial situation and roofing needs.
Frequently Asked Questions about Roofing Financing Options
What credit score is needed for a roof?
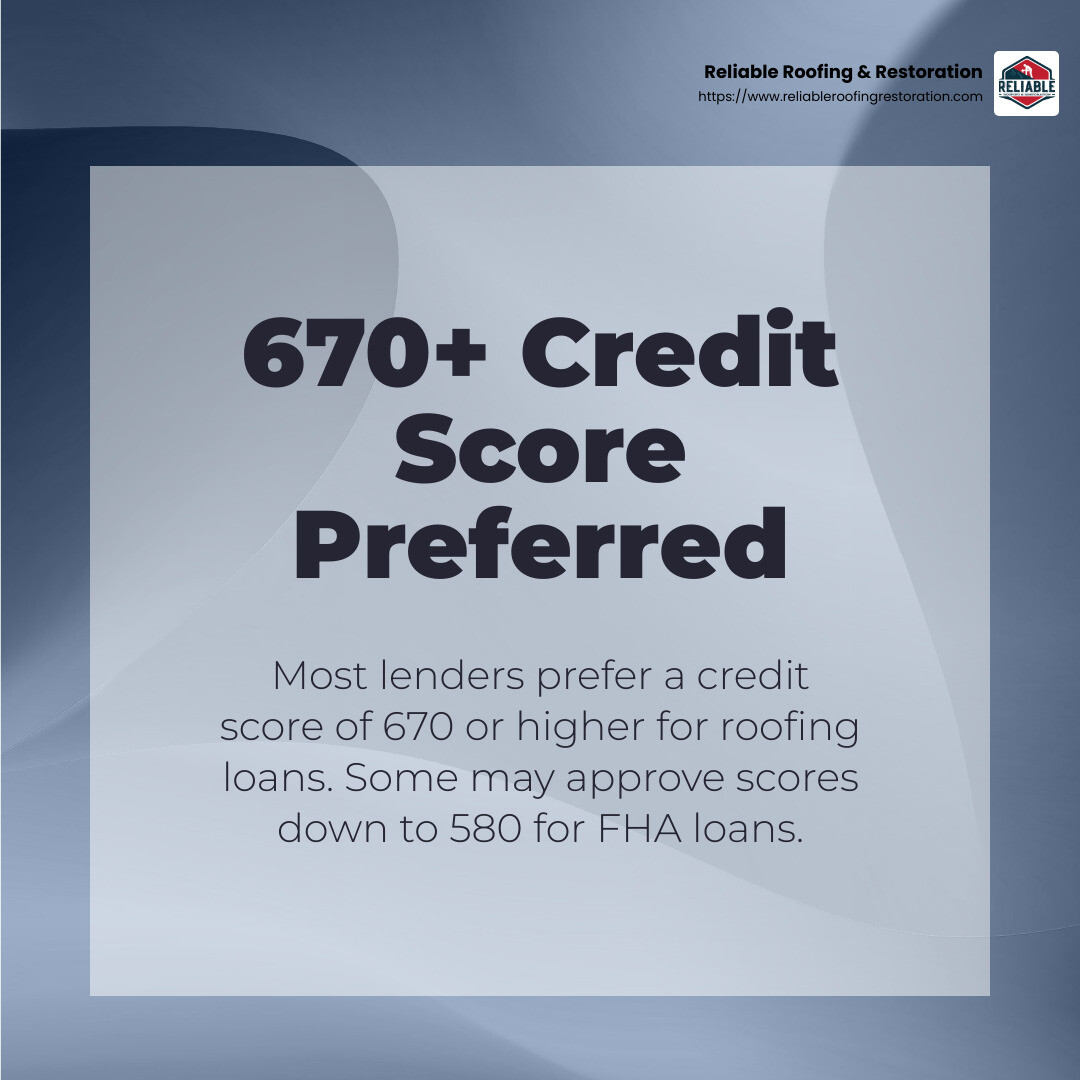
When considering roofing financing options, your credit score plays a crucial role in determining loan approval. Typically, a credit score of at least 670 is preferred by most lenders for personal loans. However, some lenders may approve scores as low as 580, especially for government-backed loans like the FHA Title 1 loan.
Can you take out a loan for a roof?
Yes, taking out a loan for a roof is common. Homeowners can choose from various loan types, including personal loans, home equity loans, and home equity lines of credit (HELOCs). Each option has different terms and conditions:
- Personal Loans: These offer fixed rates and don’t require collateral. They are often funded quickly, making them a popular choice for urgent repairs.
- Home Equity Loans and HELOCs: These use your home’s equity as collateral, potentially offering lower interest rates. However, they carry the risk of foreclosure if you default.
Repayment terms can vary, typically ranging from one to seven years for personal loans. It’s essential to choose a loan that aligns with your financial capacity and timeline for repayment.
How do most people afford a new roof?
Many homeowners rely on a combination of home equity and insurance coverage to afford a new roof. If your roof is damaged due to a storm or other covered events, homeowners insurance might cover the repair costs, minus the deductible. For planned replacements, tapping into home equity through loans or lines of credit is a common strategy, as it often offers favorable interest rates and terms.
Understanding these roofing financing options helps homeowners make informed decisions, ensuring they can manage costs effectively while maintaining their home’s integrity.
Conclusion
At Reliable Roofing & Restoration, we understand that replacing a roof is a significant investment. That’s why we are committed to providing expert craftsmanship and premium products to ensure your home is protected for years to come.
Our team specializes in high-quality residential roofing services. We use the finest materials available, ensuring durability and improved protection against the elements. With our expert craftsmanship, you can rest easy knowing your roof is built to last.
We also offer a range of roofing financing options to help make this essential home improvement more accessible. From personal loans to home equity options, our team can guide you through the process, helping you find the best fit for your financial situation.
Choosing Reliable Roofing & Restoration means choosing peace of mind. We pride ourselves on delivering exceptional service and results that stand the test of time. If you’re ready to explore your roofing options or need expert advice, visit our roof repair and replacement service page today. Let us help you protect your home with quality you can trust.